


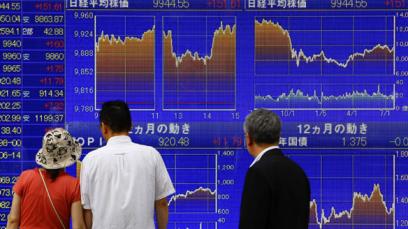
With the market all but expecting, at minimum, some tweak to the Bank of Japan Yield Curve Control, traders are trying to figure out pain points in bond markets; hence equity markets are wobbling under the threat of potentially higher global yields.
The likely outcome of any BoJ tightening is further sales of foreign bonds where EGBs are more exposed than USTs. Hence, the Euro is struggling under the weight of unknown around the BTP-BUNDS spread reactions.
Over the past 12 months, Japanese investors liquidated much of their UST holdings in the context of profoundly negative FX-Hedged returns. Japanese market participants made net sales of EUR 122bn of USTs in 2022, compared to EUR 23bn for Bunds/OATs/BTPs/DSLs combined. Therefore, there is room for EGB underperformance; hence the market wobbly a bit this morning was given the extreme unknown around global market outcome post-BoJ MPM announcements.
But once the BoJ has been fully digested, we should have fair weather sailing ahead. Still, the longer the wait, the more controversial the outcome could be.
Published by Stephen Innes, Managing Partner, SPI ASSET MANAGEMENT
Top Australian Brokers
- Pepperstone - Top Australian broker - Read our review
- eToro - Invest in ASX and international shares - Read our review




