



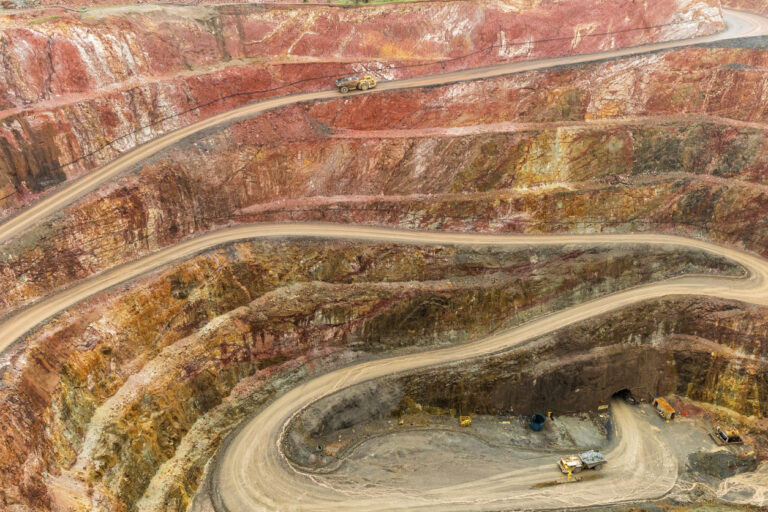
Evolution Mining shares (ASX:EVN) have been given a boost today, as the company delivered a transformational March quarter result that sent prices surging through technical resistance, as the gold and copper producer reported record cash generation and achieved a net cash position for the first time in multiple quarters.
The EVN share price is 8.91% higher at A$14.36 ahead of the closing bell, decisively breaking above the A$14 resistance level that had capped the shares for the past month. The rally came after Evolution disclosed group cash flow of A$406 million for the March 2026 quarter, equivalent to A$2,482 per ounce, alongside a shift to a net cash position of A$42 million as at 31 March 2026. The company had carried net debt in prior reporting periods, making the turnaround a clear inflection point for the balance sheet.
Markets responded enthusiastically to the dual achievement of operational strength and financial derisking as Evolution’s total cash balance stood at A$1.371 billion at quarter end, up A$404 million from the prior period, while management confirmed no debt repayments are scheduled until fiscal 2029. The extended maturity profile removes near-term refinancing pressure and provides substantial flexibility for capital allocation decisions, including organic growth investment, potential acquisitions, or enhanced shareholder returns.
Top Australian Brokers
- Pepperstone - Top Australian broker - Read our review
- eToro - Invest in ASX and international shares - Read our review
Standout Performance, Although Copper Guidance Trimmed
Two assets delivered standout performances during the quarter. Mungari generated record net mine cash flow of A$175 million, reflecting the benefits of the recently completed mill expansion and access to higher-grade ore zones. Red Lake, historically viewed as a problematic asset within Evolution’s portfolio, posted its own record with A$104 million in net mine cash flow, marking the strongest quarter since Evolution acquired the Canadian operation. The Red Lake turnaround has been a multi-year effort involving operational restructuring, capital investment, and exploration success to unlock the asset’s potential.
Group production metrics for the March quarter showed gold output of 170,000 ounces and copper production of 11,000 tonnes. The company reported all-in sustaining costs of A$2,220 per ounce for the period, a figure that remains elevated by global standards but is supported by strong gold prices. Evolution maintained its guidance for full-year fiscal 2026 gold production to be delivered at a lower cost than originally forecast, reflecting operational efficiencies and better-than-expected performance at key sites.
However, the company adjusted expectations for copper, now anticipating group copper production will land at the low end of guidance ranges. Management attributed the softer copper outlook to weather-related disruptions at the Ernest Henry operation in Queensland, where heavy rainfall impacted mine sequencing and haulage during the quarter. The copper revision tempers one element of Evolution’s diversification story, though it remains a secondary contributor to overall cash generation relative to gold.
Progress Being Made
Evolution’s organic growth pipeline continues to advance on schedule and within budget parameters. The company is progressing the BERT underground expansion at Ernest Henry and the E22 block cave development at Northparkes, both of which are expected to deliver material production increases toward fiscal 2029 and 2030. In a sector where cost overruns and schedule delays are common, Evolution’s ability to maintain discipline on these projects supports its reputation as a capable operator and provides visibility on medium-term volume growth.
Exploration activity during the period yielded encouraging results. Evolution reported high-grade drilling intercepts at both Mungari and Cowal, with ongoing programs designed to extend mine lives and add higher-margin ounces near existing infrastructure. The company also advanced multiple exploration targets in North Queensland and around Red Lake in Canada, building optionality for resource growth across the portfolio. While exploration success takes time to convert into formal reserves and production plans, the results reinforce the structural improvement story at core assets like Mungari and Red Lake.
Capital allocation remains a focal point for markets assessing Evolution’s investment case. The company paid its 26th consecutive dividend in April, with cumulative cash distributions of A$399 million returned to shareholders over time. Earlier in fiscal 2026, the board increased the fully franked dividend to A$0.20 per share, signalling confidence in the sustainability of elevated cash generation. Evolution has simultaneously reduced gearing from approximately 30% in late 2023 to low single digits by early 2026, while funding more than A$200 million per half-year in growth capital expenditure.
The combination of consistent dividends, rapid deleveraging, and sustained investment in growth projects represents the capital allocation pattern that attracts both generalist investors and income-focused funds. With the balance sheet now in net cash and no major debt maturities until fiscal 2029, Evolution will face increasing questions about potential for higher dividends, share buybacks, or strategic acquisitions if gold prices remain supportive. Management commentary to date suggests the priority remains funding organic growth, though the financial capacity for enhanced returns is now clearly established.
Evolution’s portfolio now comprises six operating mines across Australia and Canada; Cowal, Ernest Henry, Mt Rawdon, Mungari, Red Lake, and an 80% interest in Northparkes. The geographic and commodity diversification, including growing copper exposure, positions the company to benefit from multiple demand drivers in a decarbonising global economy. Evolution has also structured joint ventures in adjacent commodities, including a Nevada North lithium JV, adding further optionality to the strategic mix.
The Technical Break
From a technical perspective, the A$14 level that had previously been acting as support had flipped into resistance over the past month, and the break above could open further upside.
The March quarter results directly address several concerns that underpinned prior cautious views, including leverage, self-funding capacity, and confidence in asset performance. If sceptical views remain embedded in some analyst models, the latest operational and financial print provides a clear catalyst for upgrades or target price revisions.
Evolution’s cost base remains a vulnerability in any bear case. All-in sustaining costs of A$2,220 per ounce are well above the lowest-cost global producers, meaning the company’s cash generation is heavily dependent on sustained elevated gold prices and continued strong operational performance at Mungari and Red Lake. Any reversal in gold prices or underperformance at those key sites could quickly pressure margins and free cash flow. Markets will scrutinise coming quarters to determine whether the record net mine cash flows represent a new sustainable baseline or a peak driven by favourable grade sequencing, foreign exchange movements, or a particularly strong gold price environment.
The long-dated nature of Evolution’s major growth projects also introduces execution risk. The full benefits of the Ernest Henry BERT expansion and Northparkes E22 block cave are targeted for fiscal 2029 and 2030, meaning several years of capital deployment and operational execution lie ahead before those investments translate into material production and cash flow uplifts. Project delays, cost inflation, or changes in commodity price outlooks could alter the risk-reward calculus for those investments.
Bull Case:
- Net cash balance sheet with no debt due until FY29 eliminates refinancing risk
- Record Mungari and Red Lake cash flows prove turnaround investments are delivering results
- Lower-than-guided gold costs support margin expansion narrative as operations improve
- Organic growth projects at Northparkes and Ernest Henry progressing on time and budget
- 26 consecutive dividends demonstrate capital discipline and commitment to shareholder returns
- High-grade exploration results at Mungari and Cowal provide mine life extension optionality
Bear Case:
- All-in sustaining costs of A$2,220/oz remain elevated versus global low-cost peer group
- Cash performance heavily reliant on sustained high gold prices and strong operational quarters
- Copper production tracking low end of guidance reduces multi-metal diversification appeal
- Major growth payoffs from Ernest Henry and Northparkes delayed until FY29-30 with execution risk
- Valuation may be stretched after 8.8% rally with stock now above historical multiples
- Sustainability of record cash flows unclear; may reflect peak grade sequencing or timing
Evolution Mining has delivered a quarter that fundamentally resets the investment narrative, moving from a leveraged, turnaround story to a net cash, high-cash-flow producer with visible growth options and a track record of capital discipline.




