



Deep Yellow shares (ASX:DYL) climbed 8.44% to close at A$1.67 on Thursday, halting a five-session slide that had seen the stock give up 14.44%. Even after that pullback, the stock remains 25.56% higher over the past month of trading, reflecting how sharply sentiment has swung in both directions.
The move is supported by a notably bullish analyst call, as RBC Capital initiated coverage of the uranium developer with an Outperform rating and an A$2.05 price target, implying upside of ~23% from here. The bullish call adds a high-profile backer to a story already underpinned by visible construction progress at the company’s flagship Tumas project in Namibia and a supportive uranium market narrative.
Behind the bullish coverage
RBC Capital analyst Alistair Rankin initiated coverage with an Outperform rating, describing Deep Yellow as a “pure-play ASX-listed uranium developer with two fully-permitted assets in Tier-1 jurisdictions”, a reference to the Tumas project in Namibia and the Mulga Rock project in Western Australia. Under RBC’s rating framework, an Outperform call signals an expectation that the stock will materially outperform the sector average over a 12-month horizon.
Central to the thesis is the argument that Deep Yellow offers “compelling asymmetric upside” as the perceived financing overhang hanging over its projects is resolved and development risk is progressively “retired” through ongoing execution. That framing treats the company’s funding requirements as a resolvable issue rather than a structural barrier, with potential for a re-rating as funding clarity emerges.
Tumas Moves From Plans to Construction
The RBC initiation lands on top of a months-long run of operational milestones. In its quarterly report for the period ended 30 June 2026, released in late August, Deep Yellow reported that detailed engineering at Tumas had reached 79% completion, with bulk earthworks finished and more than A$34 million of civil and concrete works underway through contracts awarded to experienced Namibian contractors. A Final Investment Decision is targeted for the fourth quarter of 2026, subject to market conditions.
Top Australian Brokers
- Pepperstone - Top Australian broker - Read our review
- eToro - Invest in ASX and international shares - Read our review
De-risking has extended beyond engineering. The company secured a long-term Water Supply Agreement with NamWater covering construction, commissioning and operations — addressing one of the most critical operating risks for a Namibian uranium mine. It also formalised 5% local Namibian ownership in its Reptile Uranium Namibia subsidiary via Oponona Investments, a key licensing step, with Oponona’s share of expenditure carried as an interest-free loan repayable from future dividends.
Tumas is a sizeable asset on paper, with a total resource of around 118.2 million pounds of U3O8 and ore reserves of 79.5 million pounds, supporting staged initial production capacity of roughly 3.6 million pounds per year. Management has consistently stressed, however, that construction will only be fully sanctioned when long-term uranium contract prices justify a greenfield build, a disciplined stance, but one that ties the timeline to the term market rather than spot price spikes.
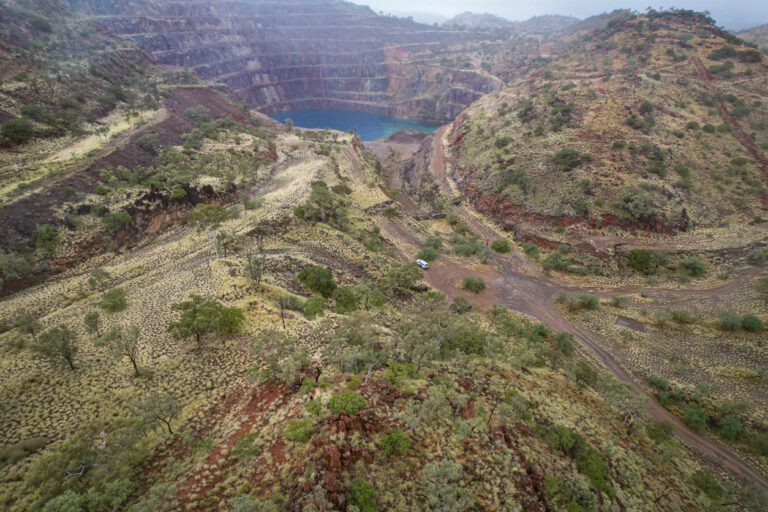
Beyond Tumas, Deep Yellow holds the fully permitted Mulga Rock project in Western Australia and recently moved to expand its longer-term pipeline, signing a binding agreement to acquire Energy Resources of Australia’s 50% interest in the Cooper Creek Joint Venture in the Alligator River Uranium Province.
What Lay Ahead
If Deep Yellow delivers FID at Tumas in late 2026 on the back of acceptable long-term uranium contracts, secures a financing package without heavy dilution, and keeps early works on schedule and budget, the stock could re-rate toward broker targets as it transitions from developer to near-term producer.
The bear case is equally clear, with the capital required to build Tumas, and eventually Mulga Rock, is substantial relative to the current cash position, meaning debt, equity or offtake-linked financing will likely be needed, with equity raising carrying dilution risk.
For now, markets appear willing to reward Deep Yellow for turning years of studies into visible construction, and RBC’s initiation gives the bull case fresh institutional weight; but with a Final Investment Decision, a major financing package and the vagaries of the uranium term market still ahead, the next leg of the share price is likely to be decided by funding clarity and execution rather than broker enthusiasm alone.
Bull Case:
- RBC’s Outperform rating and A$2.05 target imply roughly 23% upside from Thursday’s close.
- Two fully permitted Tier-1 jurisdiction assets make Deep Yellow a rare near-term producer.
- Tumas is 79% engineered with bulk earthworks complete, targeting FID in Q4 2026.
Bear Case:
- Large Tumas capex means further debt, equity or offtake financing is still required.
- FID depends on long-term uranium contract prices, leaving timing exposed to market swings.
- Construction brings cost-overrun, delay and currency risks; shares remain highly volatile.




