



BHP shares (ASX: BHP) are on course for their second-worst monthly decline of the year, down 8.3% through September to date, heading into the final three trading sessions at A$60.72.
The BHP share price is holding the support line around A$60.00, a zone that markets will be watching closely as the week plays out. The September decline is the worst performance since March’s 13.73% slump, which was triggered by the conflict between the United States and Iran, comfortably eclipsing June’s more modest 4.93% pullback, in what has been a real shift across Aussie markets.
Leading into this month’s pullback, BHP had rallied 31.43% over the previous five months, pushing the stock to new ATHs. It is worth noting that a portion of September’s decline is mechanical rather than sentiment-driven. BHP traded ex-dividend on September 3 for its final fully franked payout of US$0.99 per share, equivalent to approximately A$1.39 per share, bringing total fiscal year distributions to US$2.42 per share.
The automatic price adjustment on ex-dividend day accounted for a meaningful slice of the month’s losses, and income-oriented markets that collected the payout will view the effective yield of roughly 3.7% fully franked as a reasonable offset.
Top Australian Brokers
- Pepperstone - Top Australian broker - Read our review
- eToro - Invest in ASX and international shares - Read our review
Escondida Issue
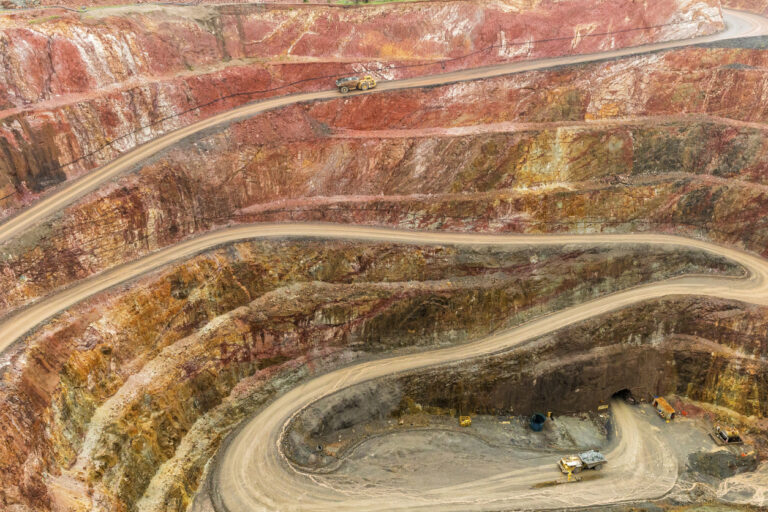
The more operationally significant development came with the suspension of activities at Escondida, BHP’s flagship copper asset in Chile and the largest copper mine on the planet. Operations were halted following a fatal maintenance accident involving a front-end loader, triggering mandatory safety audits by Chilean government inspectors before any resumption of production can be authorised. BHP holds a 57.5% stake in Escondida, which produces in excess of 1.2 million tonnes of copper annually.
With spot copper trading above US$13,000 per tonne, any prolonged disruption to Escondida’s output carries direct implications for BHP’s earnings trajectory heading into the first half of fiscal 2026. Adding to the operational uncertainty is the status of union negotiations at the mine. Labour relations at Escondida have historically been contentious, and the combination of a safety-related shutdown and active bargaining talks raises the risk that the operational pause extends beyond the initial regulatory review period.
Elsewhere across the portfolio, BHP’s Western Australia Iron Ore division delivered record production volumes and remains one of the world’s lowest-cost major iron ore producers, targeting output of more than 305 million tonnes per year. The division continues to generate substantial free cash flow that funds BHP’s longer-term capital commitments, including the Jansen potash megaproject in Saskatchewan, Canada, which reached approximately 84% completion for Stage 1 and remains on track for first production in 2027.
What Lay Ahead
From a technical standpoint, the A$60.00 support level is the key line in the sand. A sustained close below that level would represent a meaningful deterioration in the chart structure and could invite selling from momentum followers. On the other hand, a recovery back above the 50 day SMA at A$62.40 in the final sessions of September would suggest the pullback is consolidating rather than accelerating.
Markets will be watching the speed at which Chilean regulators clear Escondida to resume operations, whilst underlying copper and iron ore prices also taking a leading role. As the final quarter of the year draws close, markets appear to be happy with a period of consolidation after a five-month, 31% rally before determining which way next.
Bull Case:
- Copper now drives 54% of EBITDA, leveraging structural electrification and data centre demand.
- Free cash flow surged 83% to US$9.77 billion, underpinning dividends and capital investment.
- Iron ore division delivers record volumes at world-leading low-cost margins, providing earnings backstop.
- Jansen potash project 84% complete, adding a third major commodity growth pillar by 2027.
Bear Case:
- Escondida shutdown risks material near-term copper output loss at BHP’s flagship asset.
- £36 billion Samarco lawsuit remains unresolved, creating persistent institutional overhang.
- Broker downgrades cite stretched valuations following the 31% five-month pre-September rally.
- September technical weakness risks breaching key A$60.00 support, inviting further selling.




