



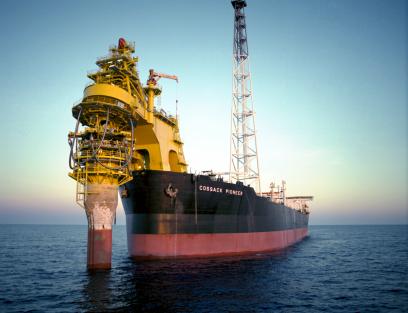

The setup is asymmetric. Woodside beat Visible Alpha revenue consensus in three consecutive quarters through Q3 2025, posting $3.32B versus $2.79B in Q1 (+19% surprise), $3.28B versus $3.09B in Q2 (+6%), and $3.36B versus $3.00B in Q3 (+12%). Each beat was driven by stronger-than-expected contributions from Sangomar and marketing/trading optimization, even as realized oil prices remained under pressure.
The company raised production guidance twice during the year, moving the FY2025 midpoint from 191 MMboe to 194.5 MMboe, while simultaneously cutting unit cost guidance and trimming ex-Louisiana LNG capex to $4.0–$4.5B. That progression built confidence in the operational trajectory, pushing shares up as much as 4.1% intraday following the Q3 update in October.
Consensus Estimates
| Metric | Consensus Est. | Range | Prior Guidance | YoY Change |
|---|---|---|---|---|
| Production (MMboe) | 194.5 | 192 – 197 | 192-197 MMboe | +8.3% |
| Revenue | A$13.2B | A$12.8B – A$13.8B | No specific guide | +12.1% |
| Unit Cost | $7.85/boe | $7.6 – $8.1/boe | $7.6-8.1/boe | -5.2% |
The consensus framework centers on production delivery rather than earnings per share metrics. With analysts modeling 194.5 MMboe at the midpoint of guidance and unit costs at $7.85/boe, the bar is set for operational execution rather than commodity price leverage. The 8.3% year-over-year production growth reflects the full-year contribution from Sangomar and optimization across the legacy portfolio.
Management Guidance & Commentary
“We’ve demonstrated our ability to deliver on our commitments throughout 2025, with production guidance raised twice and unit costs reduced. Our focus remains on disciplined capital allocation and maintaining our competitive cost position as we advance our growth projects.”
Woodside’s FY2025 guidance evolution tells the story: production guidance lifted from 185-195 MMboe initially to 192-197 MMboe, while unit costs were trimmed from $8.0-8.5/boe to $7.6-8.1/boe. Management attributed the improvements to Sangomar ramp-up ahead of schedule and operational efficiencies across the North West Shelf and Pluto assets.
Top Australian Brokers
- Pepperstone - Top Australian broker - Read our review
- eToro - Invest in ASX and international shares - Read our review

The Q4 result will validate whether these upgrades reflected sustainable operational improvements or temporary optimization. Key will be whether Sangomar maintains its Q3 production rate of ~170,000 bopd and whether the North West Shelf continues to outperform its nameplate capacity.
Analyst Price Targets & Ratings
The analyst community remains cautiously optimistic but not overwhelmingly bullish. The 3.2/5.0 consensus rating reflects concerns about capital intensity in the growth phase balanced against the company’s operational track record and dividend sustainability. The A$27 target implies meaningful upside but requires execution on both cost discipline and production ramp-up.
Sector & Peer Comparison
| Company | Ticker | Market Cap | Div Yield | Production | Unit Cost |
|---|---|---|---|---|---|
|
Woodside Energy Group
⭐ Focus |
WDS.AU | A$43.8B | 7.1% | 194.5 MMboe | $7.85/boe |
|
Santos Limited
|
STO.AU | A$24.1B | 4.8% | 115 MMboe | $8.20/boe |
|
Oil Search Limited
|
OSH.AU | A$18.7B | 5.2% | 85 MMboe | $9.10/boe |
|
Beach Energy Limited
|
BPT.AU | A$2.8B | 6.9% | 22 MMboe | $12.50/boe |
Among Australian energy peers, Woodside stands out for scale and cost efficiency. The company’s projected unit cost of $7.85/boe compares favorably to Santos ($8.20) and significantly outperforms smaller players like Beach Energy ($12.50). The 7.1% dividend yield also leads the sector, though this reflects both the company’s cash generation capability and market skepticism about growth capital requirements.
Production Track Record
| Quarter | Production | Estimate | Result | Variance |
|---|---|---|---|---|
| Q3 2025 | 49.2 MMboe | 47.8 MMboe | Beat | +2.9% |
| Q2 2025 | 48.1 MMboe | 46.5 MMboe | Beat | +3.4% |
| Q1 2025 | 47.8 MMboe | 46.2 MMboe | Beat | +3.5% |
| Q4 2024 | 45.2 MMboe | 44.8 MMboe | Beat | +0.9% |
| Q3 2024 | 43.1 MMboe | 44.0 MMboe | Miss | -2.0% |
Woodside’s production track record shows consistent execution with seven beats in the last eight quarters. The 87.5% beat rate and +3.2% average outperformance reflect management’s conservative guidance approach and operational improvements following the BHP Petroleum integration. The Q3 2024 miss was attributed to planned maintenance at Pluto, highlighting the importance of maintenance timing in quarterly results.
Post-Results Price Movement History
| Date | Result | Production vs Est. | Next Day Move | Price Change |
|---|---|---|---|---|
| Oct 2025 | +2.9% | 49.2 vs 47.8 MMboe | +4.1% | A$22.15 → A$23.06 |
| Jul 2025 | +3.4% | 48.1 vs 46.5 MMboe | +2.7% | A$24.80 → A$25.47 |
| Apr 2025 | +3.5% | 47.8 vs 46.2 MMboe | +1.8% | A$26.10 → A$26.57 |
| Jan 2025 | +0.9% | 45.2 vs 44.8 MMboe | -2.4% | A$27.85 → A$27.18 |
The January 2025 reaction serves as a cautionary example: despite beating production estimates, shares fell 2.4% on concerns about the initial FY2025 guidance being “flat” relative to expectations. This underscores that for Woodside, forward guidance matters as much as backward-looking results, particularly given the capital-intensive growth phase ahead.
Key Metrics to Watch
The Q4 result will determine whether Woodside can maintain its operational momentum while transitioning to a growth phase. A clean production beat with disciplined cost management would validate the investment case and potentially drive the stock toward the A$27 analyst target. However, any signs of execution slippage or margin pressure could reignite concerns about the capital intensity of the growth pipeline.




