



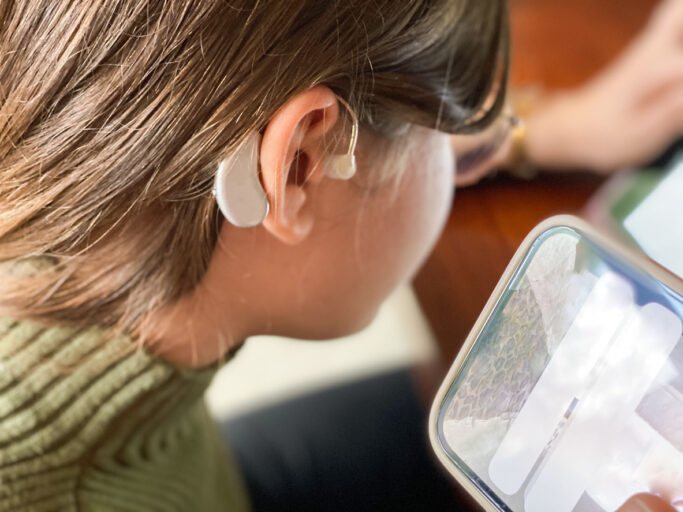
Cochlear shares (ASX: COH) suffered their worst single-day decline since listing in 1995, crashing to a ten-year low after the hearing implant manufacturer slashed its full-year earnings guidance by approximately 35% amid weakening global trading conditions.
The Cochlear share price crashed 39.41% to sit at A$101.76 ahead of the close, after touching an intraday low of A$97.88, the weakest level since 2016. After such a drop, perhaps unsurprisingly, COH shares became the worst performer on the ASX 200 index and has now fallen 61% year-to-date in 2026, wiping billions of dollars from the company’s market cap.
Earnings Downgrade Shocks Markets
In a statement to the Australian Securities Exchange on Wednesday morning, Cochlear announced it now expects underlying net profit for the 2026 financial year to land between A$290 million and A$300 million, down sharply from previous guidance of A$435 million to A$460 million. The midpoint of the new range represents a cut of approximately 37%, stunning markets that had grown accustomed to the company’s premium valuation and consistent execution.
The downgrade follows a pattern of progressive disappointments over the past year. In February 2026, Cochlear reported first-half underlying net profit of approximately A$195 million, down 9% year-on-year, and guided to the lower end of its then-current range. Prior to that, the company had trimmed guidance by roughly 5% at the lower end, citing slower growth in developed markets and services revenue weakness.
Top Australian Brokers
- Pepperstone - Top Australian broker - Read our review
- eToro - Invest in ASX and international shares - Read our review
Multiple Headwinds Complicate Path
Cochlear attributed the sharp downgrade to a confluence of operational, policy, and currency headwinds across its key markets. In Western Europe, surgical volumes have been “constrained,” resulting in growing waiting lists for cochlear implant procedures in major markets including the United Kingdom and Germany. Industrial action in Italy and Spain has further restricted surgical throughput, limiting the company’s ability to convert demand into revenue.
The United States market, which had been trading in line with expectations through mid-February, saw volumes decline materially in March. While the company did not elaborate on the specific drivers of the US slowdown, the timing suggests broader macro pressures may be affecting elective medical procedures.
In emerging markets, where growth has remained solid, Cochlear warned of expected order cancellations in the Middle East. The company also flagged that reduced reimbursements in China would lower premium-tier sales in the second half of the fiscal year, adding policy risk to its list of challenges.
Beyond volume pressures, lower production levels are expected to compress gross margins, while a stronger Australian dollar is forecast to reduce earnings by approximately A$25 million to A$30 million after tax in the second half. In response, Cochlear said it is “reshaping components of our organisation to deliver a more flexible and lower cost-to-serve cost base,” signalling restructuring efforts are underway.
Despite the near-term setback, Chief Executive Officer Dig Howitt emphasised the structural opportunity ahead and the company’s market-leading position. In the company’s statement, Howitt said: “Addressing hearing loss in adults and seniors continues to be treated as a discretionary intervention, highlighting the importance of our strategy to medicalise hearing loss so that treatment is recognised as an important health priority.”
Howitt pointed to strong adoption of the Nucleus Nexa System across developed markets, with very positive customer feedback and growing interest in the system’s potential to improve hearing outcomes further. He noted that market share has been improving as contracting for the new system is completed.
Looking to the innovation pipeline, Cochlear highlighted progress toward commercialisation of next-generation implants. Two clinical studies for regulatory approval of a drug-eluting electrode are now fully recruited, with initial results under analysis. Additionally, two studies for regulatory approval of a totally implantable cochlear implant are underway, representing potential growth drivers in the medium term.
The company also pointed to resilience in its services business, which continues to expect strong revenue growth in the second half. Third-quarter services revenue rose 13% on a constant currency basis compared to the prior year, providing some offset to the implant volume weakness.
Shifting Tides See Cochlear Shares Lose Confidence
The magnitude and timing of the downgrade have raised questions about forecasting accuracy and management’s visibility into trading conditions. Moving from guidance of A$435 million to A$460 million in late February to A$290 million to A$300 million just eight weeks later represents a significant reversal that has damaged credibility with markets.
Analysts who had maintained bullish views on the stock are now reassessing their assumptions. Approximately three months ago, RBC Capital upgraded Cochlear from Sector Perform to Outperform with a price target of A$325, arguing that 2025’s de-rating was driven by temporary earnings disappointment and that 2026 would see an inflection in growth. Those assumptions have been invalidated by today’s announcement, and price targets across the sell-side are expected to be slashed in coming days.
The valuation debate now centres on whether Cochlear deserves to trade at a premium multiple given the earnings volatility and exposure to policy and capacity risks. At current levels, the stock trades at a significant discount to its historical valuation, but markets must weigh whether this reflects appropriate risk pricing or an opportunity to buy a quality franchise at a depressed level.
Bears argue that the company faces a structural reset in earnings power, with multiple headwinds converging and limited visibility on when conditions will normalise. The pattern of repeated downgrades over 12 to 18 months suggests forecasting challenges may persist, and the risk of further disappointment cannot be ruled out.
Bulls counter that demand drivers remain intact, with ageing populations and under-penetration of cochlear implants supporting long-term structural growth. They point to Cochlear’s market leadership, strong technology moat, and late-stage pipeline as reasons to believe current issues are cyclical rather than structural.
What is clear is that Cochlear shares face a challenging period as the company navigates operational disruption, policy uncertainty, and margin pressure. At least for now, bears are firmly in charge, and the test of A$100 as potential support could be vital in shaping what happens next.




